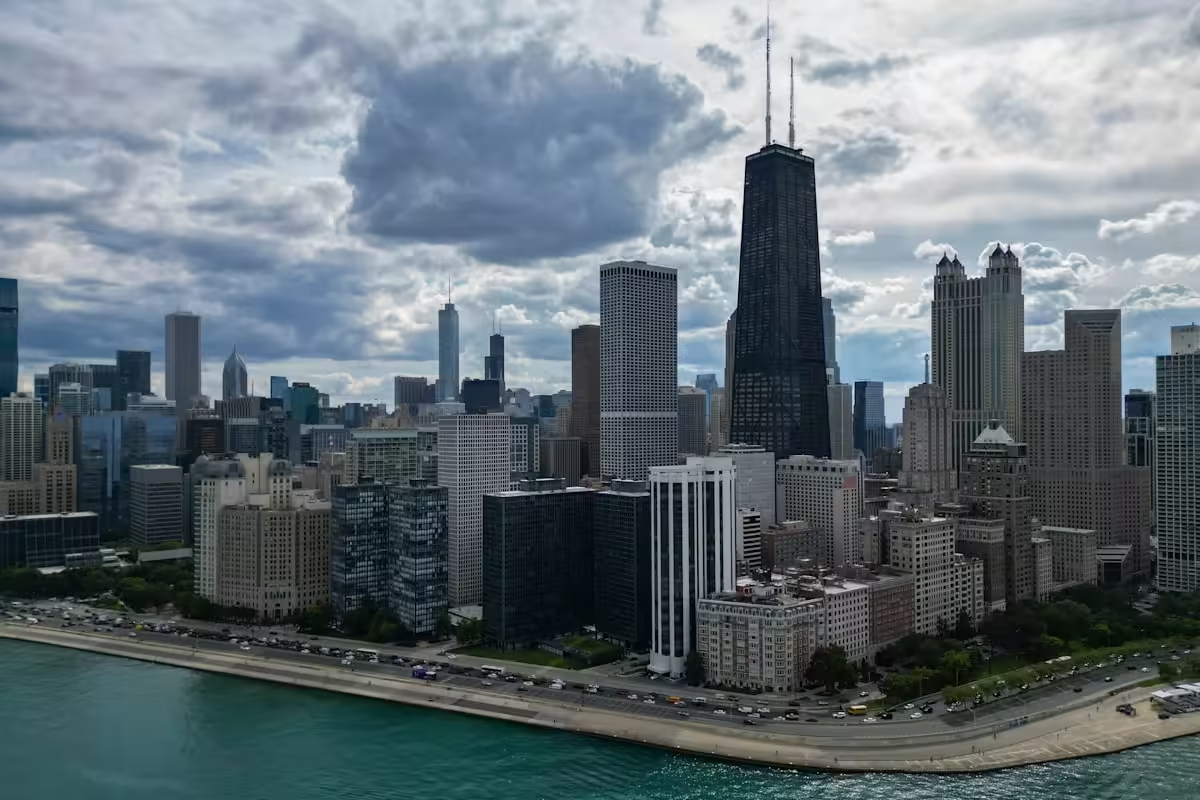
In one of America’s hottest housing markets, not even 7% mortgage rates seem to be slowing down sales. Multiple-offer situations remain a regular occurrence. Realtors prep their buyers to expect months-long searches, while motivated sellers can usually wrap up the entire transaction in a week or less. That’s the current state of affairs in Chicago,
In one of America’s hottest housing markets, not even 7% mortgage rates seem to be slowing down sales.
Multiple-offer situations remain a regular occurrence. Realtors prep their buyers to expect months-long searches, while motivated sellers can usually wrap up the entire transaction in a week or less.
That’s the current state of affairs in Chicago, where home prices are up 6.7% this year, the most of any large metropolitan area. By that measure, the Windy City’s housing market is moving faster than the perennially hot New York region, as well as San Francisco, where artificial intelligence wealth is transforming the market.
Realtors have multiple theories for the continued market heat. Low inventory is a major part of the problem: Greater Chicago had just 16,700 homes on the market as of October, a nearly 60% drop from the typical pre-pandemic fall level of about 40,000. And both the city and Illinois as a whole have long ranked near the bottom on measures of homebuilding activity.
Then there’s the city itself: While prices are rising fast, Chicago remains one of just a few major metropolitan areas with big-city amenities and a moderate cost of living. As affordability becomes a bigger concern for millions of Americans, the secret appears to be getting out.
Jeremy Padoor, a real estate broker in the city at Cross Street, said his friends in pricier cities like New York and Los Angeles are floored by the listings he shares online. Compared to the coasts, money stretches further in Chicago.
“You can get a 3-bedroom condo for $600,0000 in a great neighborhood,” Padoor said. “That’s insane. I think some clients of mine and maybe the general population see it as Chicago is still really affordable for what it has to offer.”
That relative affordability helped push Jacquelyn Young-Bowers, 22, to purchase her first home in Chicago earlier this year. The Los Angeles native accepted a job in the city as a data analyst after college and found she was paying less in rent than she would for a similar place in her hometown.
Realizing that a $400,000 budget could land her a mortgage payment similar to her rent, she set out in search of a two-bedroom, two-bathroom apartment in some of the city’s Near North Side neighborhood, an area known for easy waterfront access and a strong dining and arts scene. She toured more than a dozen options, nixing some when she realized sellers were listing low in hopes of sparking a bidding war, and others when sellers refused to budge on pricing even as their units lingered on the market.
“It was definitely difficult,” Young-Bowers said. “I was finding a lot of cute places, but they were just out of my budget.”
Pickings were particularly slim in winter, when she started hunting, but by spring she had slightly more options. Over time, she also trimmed her wishlist from two bathrooms to one and gave up on her dream of an in-unit washer-dryer.
Last spring, she toured an apartment that had the location and abundant natural light she wanted, but it had been lingering on the market since the depths of winter. That seller was willing to negotiate on price, and she closed in April.
“Playing the waiting game and trying to stay patient and wait for more things to open up really helped me,” she said.
These days, it’s not unusual for the North and West Side neighborhoods popular with young urban professionals to have less than a month of inventory available, said Padoor, who frequently works in those areas. Months of inventory measure how long it would take to sell all homes currently on the market, and anything below three months indicates a market tilted strongly toward sellers.
Padoor tells many buyers to expect to be among multiple offers and be prepared to waive or pare down common contingencies to be more competitive.
This drone photo features a residential neighborhood in Elmhurst, Ill., on a sunny fall afternoon. Elmhurst is a western suburb of 45,000 residents located about 16 miles west of downtown Chicago. ·Kevin Lewis via Getty Images
It’s a similar story in suburban Chicago, where homes in close-in suburbs with amenities like commuter rail, established downtowns of their own, and trendy local restaurants remain in high demand.
In June, one recently renovated home Kristi Gorski listed in DuPage County, immediately west of the city, garnered 37 offers. Even in a hot market, that level of interest is an outlier, but well-kept homes move quickly.
“People are going crazy over the good ones,” said Gorski, an agent with DPG Real Estate Agency in Lisle, Ill.
And though mortgage rates lingering above 7%, combined with the typical seasonal slowdown, have cooled sales in many parts of the country, Chicago has proven relatively immune, at least so far. Inventory remains too scant, and the region’s deep pool of wealthy buyers and downsizers paying cash removes some of the sting of higher rates.
“The fall is typically a cooler market, but we’re still seeing multiple offers in a lot of these places,” said Sarah Africk, a broker with @properties Christie’s International Real Estate in Chicago’s Gold Coast neighborhood.
Claire Boston is a senior reporter for Yahoo Finance covering housing, mortgages, and home insurance.
Pleskmedia Media Is a Global News Platform Covering the Latest Developments and Breaking Stories from Around The World, Including World News, Business, Finance, Technology, Health, Politics, Science, Entertainment, Sports, and More.