Irish Continental Group: Event Trigger And Recent Share Moves Irish Continental Group (LSE:ICGC) has drawn fresh attention after its recent share performance, with the stock flat over the past day and week but down 3.3% over the past month. Despite the softer 30-day share price return of 3.3% and a modest 90-day decline of 1.5%,
Irish Continental Group: Event Trigger And Recent Share Moves
Irish Continental Group (LSE:ICGC) has drawn fresh attention after its recent share performance, with the stock flat over the past day and week but down 3.3% over the past month.
Despite the softer 30-day share price return of 3.3% and a modest 90-day decline of 1.5%, Irish Continental Group has delivered a 22.4% year to date share price gain, supported by a 1-year total shareholder return of 30.1% and an 88.2% total shareholder return over three years. This suggests momentum has cooled recently after a strong multi year run.
The share price has cooled after a strong three year run, yet Irish Continental Group still screens at about a 70% discount to estimated intrinsic value. Is the market being cautious, or are the models too generous?
Preferred P/E Multiple Of 15.7x: Is It Justified?
Irish Continental Group screens very cheaply against the SWS DCF fair value estimate, yet on a simple earnings multiple the shares look a touch expensive relative to close peers. The last close at £6.55 still implies a 69.6% discount to the SWS future cash flow value, which stands at £21.54 per share.
The SWS DCF model projects Irish Continental Group’s future cash flows and then discounts them back to today using a required return. That process aims to capture both the size and timing of those expected cash flows, rather than just what the business earned in the most recent year.
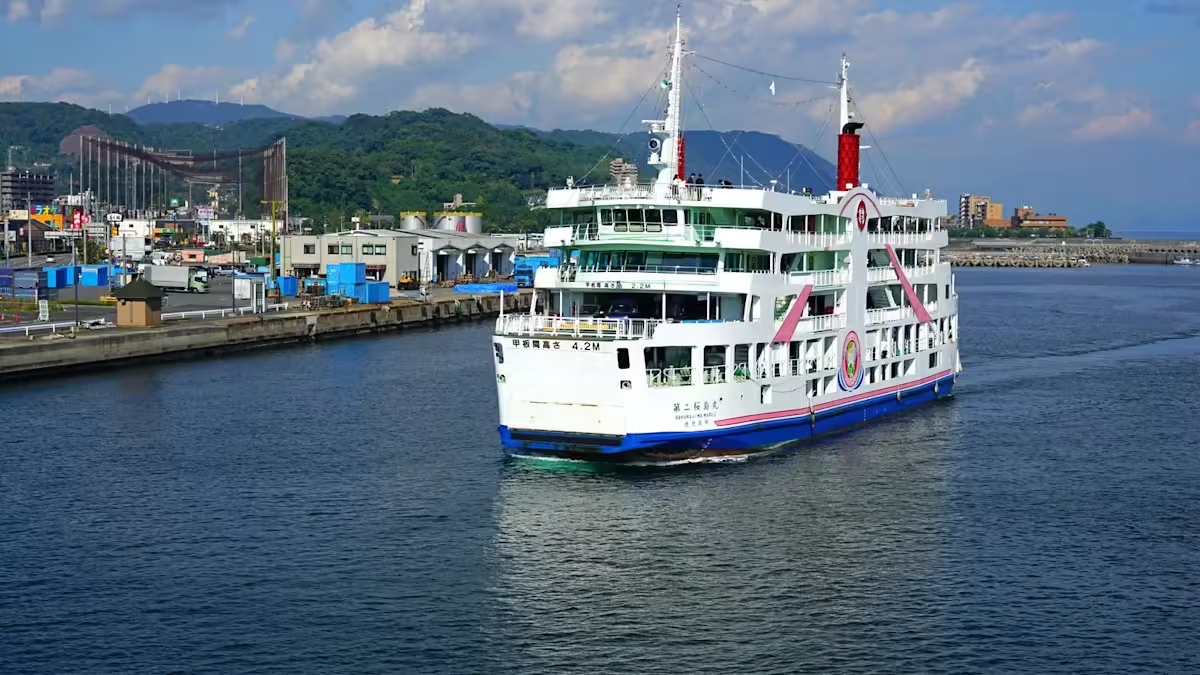
For a ferry and container shipping operator with £716.7m of revenue and £74.2m of net income, cash generation and capital intensity are central questions. The DCF approach leans heavily on Irish Continental Group’s history of moving from losses into profitability over the past five years, with earnings growing at 32.3% per year over that stretch and 13.3% in the last twelve months. High quality earnings and a 26.2% Return on Equity sit on one side of the ledger, while a high level of debt and full reliance on higher risk funding sit on the other.
Investors weighing the £6.55 market price against the £21.54 SWS DCF output are essentially judging how durable that earnings profile is in a sector where forecast revenue growth sits at 3.7% per year. The DCF result implies the market is applying a substantial discount to those projected cash flows, even with Irish Continental Group’s P/E of 15.7x sitting slightly above the European shipping industry average of 15.6x and above the 12.3x peer group average.
Still, Irish Continental Group faces clear pressure points if fuel costs stay elevated or if freight volumes across its Irish and UK routes soften meaningfully.
Irish Continental Group: What The P/E Is Really Telling You
The headline DCF result paints Irish Continental Group as heavily undervalued at £6.55 versus a £21.54 fair value. The P/E story is different. At 15.7x, the shares trade slightly above the European shipping industry on 15.6x and well above the 12.3x peer average.
That gap means anyone leaning on earnings multiples is paying a premium today for a business whose forecast revenue increase sits at 3.7% a year, only a touch ahead of the wider UK market at 3.3%. The question is whether Irish Continental Group has already earned that mark up, or if the multiple leaves less room for error if conditions tighten.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Irish Continental Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match – so you never miss a potential opportunity.
Next Steps
If the mixed signals on Irish Continental Group leave you on the fence, that is healthy. Act quickly, stress test the numbers for yourself, then weigh the 3 key rewards and 1 important warning sign
Looking For More Investment Ideas Beyond Irish Continental Group?
If Irish Continental Group has sharpened your focus on valuation and quality, do not stop here. Your next outperformer could already be on the radar.
This article is general in nature and was produced with the assistance of AI automation, based on data and analysis from Simply Wall St. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Companies discussed in this article include ICGC.L.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email [email protected]
Pleskmedia Media Is a Global News Platform Covering the Latest Developments and Breaking Stories from Around The World, Including World News, Business, Finance, Technology, Health, Politics, Science, Entertainment, Sports, and More.